Using Advance TT Payment When Buying From Bangladesh: Bank Rules and Tips
Advance TT to Bangladesh means paying before shipment. This guide covers the advance share, staged releases, Bangladesh Bank advance conditions, costs, documents and checks that limit buyer risk.
Short answer
An advance TT to Bangladesh means paying before shipment, so the buyer carries the risk until the goods are made and shipped. Limit that risk by agreeing a staged advance share with checkable milestones, a written refund clause, and the OUR charge code per stage, and by confirming each beneficiary bank credit rather than the send.
On this page
Key takeaways
An advance TT pays before shipment, so the buyer carries the risk until the goods are made and shipped.
Stage the advance: a share before production, a share on a checkable milestone such as inspection, and a balance on shipment documents.
On the Bangladesh side, the seller bank obtains an Advance Receipt Voucher declaration and checks the contract, capability, interest-free terms, and one-year execution window.
Agree the OUR, SHA, or BEN charge code and the refund route in the contract before instructing any leg.
Exportain does not move the TT: payment settles directly with the supplier, and verification is a document and photo review, not a factory inspection.
An advance TT changes the order of a normal trade payment. Instead of paying after shipment, or paying a balance against shipping documents, you send money before the goods are made or shipped. Cash in advance means the buyer pays before the goods are shipped, and the seller receives funds and then fulfils the order.1 This guide is not about how a TT travels in general, but about what paying early does to your risk, costs, and the bank checks on the Bangladesh side. For a seller, an advance funds materials and production. For a buyer, it removes the leverage a balance payment provides: once credited, it cannot be held back if production slips or shipment never happens. The controls that replace that leverage are the advance share, the staged milestones, the refund clause, and the pre-send checks.
Why this matters for buyers and sellers
The risk spectrum in international payment methods runs from seller-protected to buyer-protected, and cash in advance sits at the seller-protected end: it carries no payment risk for the seller but puts all risk on the buyer.1 From the buyer side, the methods that protect you most are the ones where payment follows documents or delivery.1
That asymmetry is why sellers ask for an advance and why buyers should negotiate its size rather than accept it as a fixed term. A seller needing fabric or inputs before production has a reason to ask for a first stage. A seller asking for the full order value before any milestone, on a first order, with no inspection right and no refund clause, asks you to carry every risk.
Step-by-step: how it works
An advance TT order works best as a staged schedule.
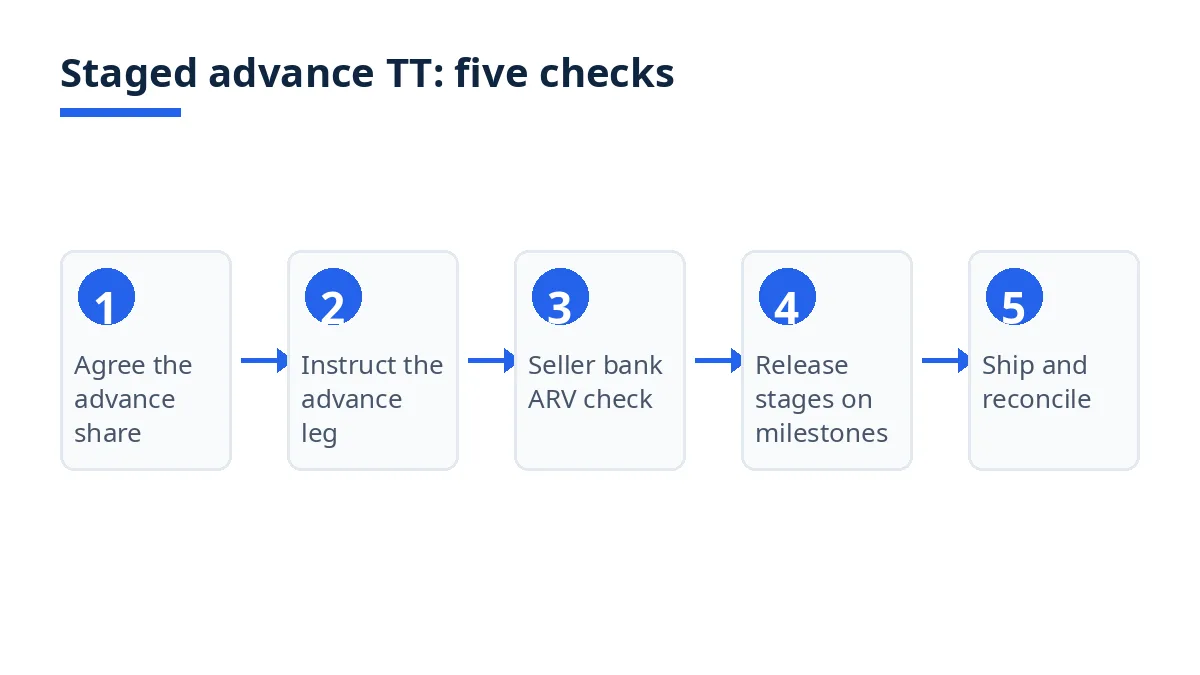
Decide the advance share before you discuss price. Agree the percentage paid before production, the percentage following a checkable milestone, and the percentage remaining for shipment. Write each stage, its trigger, and its amount into the contract or proforma invoice.
Write the advance clause, including the refund route. State the currency, total value, stages, triggers, charge code, and reference. Add what happens if the export is not executed: refund, currency, and bank route. The Bangladesh rules allow the seller bank to refund a non-executed advance, using Exporters Retention Quota funds first, so agree that route in writing before you send.2
Collect the seller current written bank details. Use the beneficiary legal name exactly as registered on the account, the account number, the beneficiary bank name and branch, the SWIFT/BIC code, the amount, currency, purpose of payment, and charge code. Your bank verifies both sides, screens against anti-money laundering and sanctions lists, and may ask for invoices or contracts.3
Instruct the advance leg with its purpose stated clearly. State on the instruction that the payment is an advance receipt for goods to be exported, with the invoice or order reference in the remittance information. On the Bangladesh side, the seller bank obtains a declaration from the beneficiary on the Advance Receipt Voucher, certifying the purpose, and reports it to the online reporting module.2
Confirm the credit, then track each staged release the same way. Your bank confirmation proves an instruction was sent. Only the beneficiary bank credit proves the seller received the money. Finance teams should reconcile confirmations with the instruction, accounting for deductions and exchange differences.3 Check the milestone document, then instruct, then confirm the credit at every stage.
Close the file against the shipment. Reconcile amounts sent and credited, deductions, and exchange rates per stage.
Costs, timelines and documents
What are the typical costs and timelines?
An advance TT carries the same cost components as any TT, but staging multiplies them: each stage is a separate transfer with its own sending fee, intermediary deductions, and exchange-rate margin. One TT guide lists four components: a sending bank fee, intermediary bank fees, an exchange-rate markup, and a receiving bank fee, with intermediary fees of USD 10 to 35 per bank and receiving fees often of USD 5 to 25, deducted from the transfer amount, and a markup of 1 percent to 5 percent above the mid-market rate, built into the quoted rate.4
The charge code decides who bears the middle costs on each leg. Under OUR, you pay all fees, so the recipient should receive the full amount. Under SHA, you pay your sending bank fee and the recipient pays intermediary and receiving fees. Under BEN, the recipient pays all fees, deducted from the amount received.4 For an advance leg, OUR protects the amount the seller needs to start production; a SHA shortfall can leave the seller short of that budget. Write the code into the contract for each stage, not only onto the bank form.
Timelines follow the same pattern as any TT. One guide reports international TTs typically taking 1 to 5 business days, depending on destination, currencies, and cut-off times.4 Transfers submitted after a bank daily cut-off are processed on the next business day.3 Compliance screening can extend the wait further.3 Do not promise a production start date before allowing for cut-off, weekends, holidays, and a possible compliance hold.
Example figures: an Australian buyer orders cotton canvas tote bags for USD 32,500, paid as 30 percent advance of USD 9,750 before production, 40 percent of USD 13,000 on a passed pre-shipment inspection, and 30 percent of USD 9,750 against a copy bill of lading. Example figures: if the advance leg is sent under SHA with USD 60 in deductions, the seller bank credits USD 9,690, leaving a USD 60 gap in the production budget. The amounts are illustrative only.
Which documents are needed?
To instruct an advance leg, you need the seller full written bank details, your bank instruction with the advance purpose and reference, and the contract showing the staged schedule. Keep the inspection report for any inspection stage, the credit confirmation for each stage, and the shipping documents for the balance stage.
Bangladesh-specific rules and tips
The Bangladesh rules for advance receipts sit in the Bangladesh Bank consolidated circular on export trade transactions, FEPD-1 Circular No. 26, dated 30 July 2026.2 They are bank rules for the seller side, separate from anything Exportain offers, setting conditions the seller bank must satisfy before paying the advance out.
Before paying out money against a remittance whose stated purpose is an advance receipt for goods to be exported, the authorized dealer bank should obtain a declaration from the beneficiary on the Advance Receipt Voucher, with a report to the online reporting module.2 The bank must also be satisfied on five points: the exporter holds an irrevocable letter of credit or contract; past performance is satisfactory and capability adequate; the advance bears no interest; the export is executed within one year of receipt; and if the export is not executed, the bank may allow a refund, using Exporters Retention Quota funds first and the remainder from Taka accounts.2 The one-year instruction does not apply to advances against performance bonds, bank guarantees, or standby letters of credit.2
Three buyer tips follow from those conditions. First, a written contract is not optional paperwork: it is one of the conditions the seller bank checks, so paying on messages alone weakens the seller bank route. Second, the one-year window is a planning limit, not a delivery promise: agree dates well inside it. Third, the refund route in the rules runs through the seller bank, so it is slower than your own refund clause.
Two further Bangladesh rules shape how an advance order closes. The prescribed repatriation period for export proceeds is four months; if full proceeds are not received within it without Bangladesh Bank authorization, the exporter faces action under the foreign exchange rules.2 Transport documents also carry an advance-specific exception: documents of title to cargo may be drawn to the order of the importer only if the shipment is made against full payment received in advance through an authorized dealer bank and it is a requirement of the export letter of credit or contract.2 If a seller offers to draw documents directly to you on a part-payment advance, ask which condition it relies on, and get the answer in writing through the seller bank route. One narrow exception covers small online retail exports: for small-value business-to-consumer exports on an e-commerce website, no EXP Form declaration is required for values up to USD 1,000 or equivalent, where payment was received prior to shipment.2
Mistakes and red flags
What are the most common mistakes?
Paying the full value in advance on a first order. A full advance removes every later check. Where the relationship is new, a staged schedule, an inspection stage, or a bank undertaking keeps some protection in your hands. One payment-method guide states that for a new first order, a letter of credit is the appropriate choice for a large value.1
Leaving the refund route out of the contract. The bank rules allow a refund if the export is not executed, but they do not write your refund deadline, currency, or notice procedure. Without a contract clause, a refund becomes a later negotiation.
Sending an advance leg under an unagreed charge code. A SHA default can leave the seller short on the stage meant to fund production. Agree OUR, SHA, or BEN for each stage in the contract.4
Treating a sending confirmation as a credit. Your bank confirmation proves an instruction was sent. Only the beneficiary bank credit proves receipt.3
Acting on changed bank details sent by email alone. If bank details change after you agreed the advance schedule, stop and verify through a contact you already trust before sending anything. A changed account on an advance leg is the highest-value form of payment diversion, because the money leaves before any goods exist.
Ignoring the one-year execution window. An advance that sits unexecuted drifts toward a regulatory deadline as well as a commercial one. Diarise the receipt, production, and shipment dates together, and raise delays early.
Red flags that justify pausing include pressure to pay urgently outside the agreed schedule, a beneficiary name that does not match the contracting company, refusal to provide written bank details or a written contract, and any request to split the advance to an unrelated third party.
Checklist
Answer every line in writing before you instruct any advance leg.
Advance share agreed for production, inspection, and shipment stages, each with its trigger.
Contract signed, stating currency, total value, stages, triggers, charge code, and reference.
Refund clause agreed: deadline, currency, bank route, and notice procedure if not executed.
Beneficiary legal name matches the contracting company exactly, from the seller written instruction.
Account number, beneficiary bank and branch, and SWIFT/BIC code checked character by character, with a second person reading back.
Any change to bank details verified through a separate, known contact channel.
Purpose of payment states an advance receipt for goods to be exported, with the invoice or order reference.
Charge code agreed per stage, with the expected credited amount stated for the advance leg.
Cut-off times, weekends, holidays in both countries, and compliance holds allowed for in the timetable.
Credit to be confirmed by the beneficiary bank, not assumed from your sending confirmation.
One-year execution window diarised from the advance receipt date, with production and shipment dates inside it.
Amount sent and credited, deductions, exchange rate, and credit date reconciled per stage and filed.
How Exportain helps
Exportain is a marketplace where buyers find Bangladeshi suppliers, post requests for quotation, and compare replies. That role is separate from the bank transfer: the advance TT runs between your bank and the supplier bank, and Exportain does not move it. On the buying journey, payment is settled on the accepted terms directly with the supplier, with inspection and shipment conditions agreed in writing first.5 When you accept a quotation, its terms, including payment terms, are recorded in the order record.5
Use the platform to get the advance clause right before you go to your bank. Browse suppliers and post the quantity, delivery term, and advance schedule on the RFQ board so replies quote against the same terms. If a supplier asks for a funds hold, you can pay it by card or decline it, and Exportain keeps a paid hold until the supplier has filed an export clearance document and you have confirmed the trade complete.5 That hold is a platform mechanism, not a bank guarantee and not a substitute for the contract controls. Read the badges for what they record: verification is a document and photo review by staff, not a factory inspection, and membership plans never grant a trust badge.6 A badge does not replace your own checks, the inspection stage, or the refund clause. For the bank-undertaking alternative, read the LC payment meaning guide, and for general transfer mechanics, read the TT payment meaning in shipping guide.
FAQs
What should I know first about advance TT?
Know first that an advance TT pays before shipment, so the buyer carries the risk until the goods are made and shipped. Cash in advance means the buyer pays before the goods are shipped, and the seller then fulfils the order.1 Protection comes from the advance share, staged triggers, inspection stage, and refund clause, not the transfer itself.
What are the typical costs and timelines?
Costs combine a sending bank fee, intermediary bank fees, an exchange-rate markup, and a receiving bank fee, shaped by the OUR, SHA, or BEN code, and each staged leg can carry its own set of those costs.4 One guide reports intermediary fees of USD 10 to 35 per bank, receiving fees often of USD 5 to 25, and a markup of 1 percent to 5 percent above the mid-market rate.4 Timelines run from 1 to 5 business days per leg, lengthened by cut-off times, holidays, and compliance checks.3
Which documents are needed?
To instruct an advance leg, you need the seller full written bank details, your bank instruction stating the advance purpose and reference, and the contract or proforma invoice showing the staged schedule. Keep the inspection report for any inspection stage, the credit confirmation for each stage, and the shipping documents for the balance stage. On the Bangladesh side, the seller gives the Advance Receipt Voucher declaration.2
What are the most common mistakes?
The most common mistakes are paying the full value in advance on a first order, leaving the refund route out of the contract, sending an advance leg under an unagreed charge code, treating a sending confirmation as a credit, and acting on changed bank details sent by email alone.
Next steps on Exportain
Browse suppliers, then post your quantity, delivery term, and staged advance schedule on the RFQ board so suppliers quote against the same payment clause. Before you instruct your bank, read the LC payment meaning guide.
Sources
- 5 Common Payment Methods for International Trade. Statrys (accessed )
- Consolidated circular on foreign exchange regulations — export trade transactions (FEPD-1 Circular No. 26, July 30, 2026). Bangladesh Bank (accessed )
- The Complete Telegraphic Transfer Guide for Payment Operations Teams. Rapyd (accessed )
- Telegraphic Transfer (TT): What It Is & How It Works. Statrys (accessed )
- How to source and buy from Bangladesh. Exportain (accessed )
- Supplier verification: Earn trust badges buyers can see. Exportain (accessed )
About the author
Sourcing from Bangladesh?
Post a request for quotation and suppliers on Exportain can send you their quotes directly.
Post an RFQ