Using Usance (deferred) Letter of Credit When Buying From Bangladesh: Bank Rules and Tips
Usance LC for Bangladesh buyers: payment at maturity, not at presentation — how the tenor anchor fixes the maturity date, the seller's hold-or-discount choice, Bangladesh Bank discounting and repatriation rules, and the mistakes that stop acceptance.
Short answer
A usance LC pays at a maturity date fixed by the credit, not at presentation. On a complying presentation the bank incurs a deferred payment undertaking or accepts a time draft, the tenor clock runs from the anchor in the credit, and payment falls due at maturity. State the form, tenor length and anchor in the contract, confirm the maturity date in writing after acceptance, and check a long tenor against Bangladesh's four-month repatriation period.
On this page
Key takeaways
A usance LC pays at maturity, not at presentation: on a complying presentation the bank incurs a deferred payment undertaking or accepts a time draft, and the tenor clock then runs from the anchor stated in the credit.
The tenor anchor decides the maturity date, so a clause saying only '90 days usance' is incomplete: state deferred payment or acceptance, tenor length, and whether the period runs after the transport document date, presentation, acceptance, or sight.
The seller's choice is hold to maturity or discount: discounting brings funds sooner for a financing cost but does not move the buyer's maturity date, and reimbursement is due at maturity whether or not the nominated bank prepaid.
On Bangladesh orders, check the tenor against the four-month export-proceeds repatriation period, confirm the EXP Form and transport-document route, and ask about the seller's discount route before issuance where early funds are needed.
A usance letter of credit, also called a deferred credit, pays not at presentation but on a later date fixed by the credit, the maturity date, once the bank has determined that the presentation complies. The buyer gains a credit period; the seller must decide whether to wait for maturity or discount sooner.
UCP 600, the Uniform Customs and Practice for Documentary Credits, 2007 Revision, is the rule set most documentary credits are issued under, approved in October 2006 and implemented on 1 July 2007.1 Under those rules, honour means to pay at sight for sight payment, to incur a deferred payment undertaking and pay at maturity for deferred payment, and to accept a bill of exchange, or draft, drawn by the beneficiary and pay at maturity for acceptance.2
See the letter of credit (LC) guide for the short definition. This guide covers one form only: usance, for a buyer ordering from Bangladesh.
Why this matters for buyers and sellers
For the buyer, a usance credit buys time between shipment and payment: goods may be cleared and sold before maturity. That benefit is not inspection protection: banks deal with documents and not with goods, services or performance to which the documents may relate.2 If the documents comply, the bank undertaking stands, and a quality dispute is a matter under the sale contract.
For the seller in Bangladesh, a usance credit is a financing decision, not just a payment term. The seller ships and presents documents, receives an acceptance or a deferred payment undertaking instead of money, and then chooses: hold it to maturity, or discount it for funds sooner at a financing cost. A seller needing cash for fabric, labour, or the next order will price that choice into the offer, or ask for a shorter tenor.
Step-by-step: how it works
A usance credit runs on two clocks: examination, which decides compliance, and tenor, which runs from anchor to maturity.
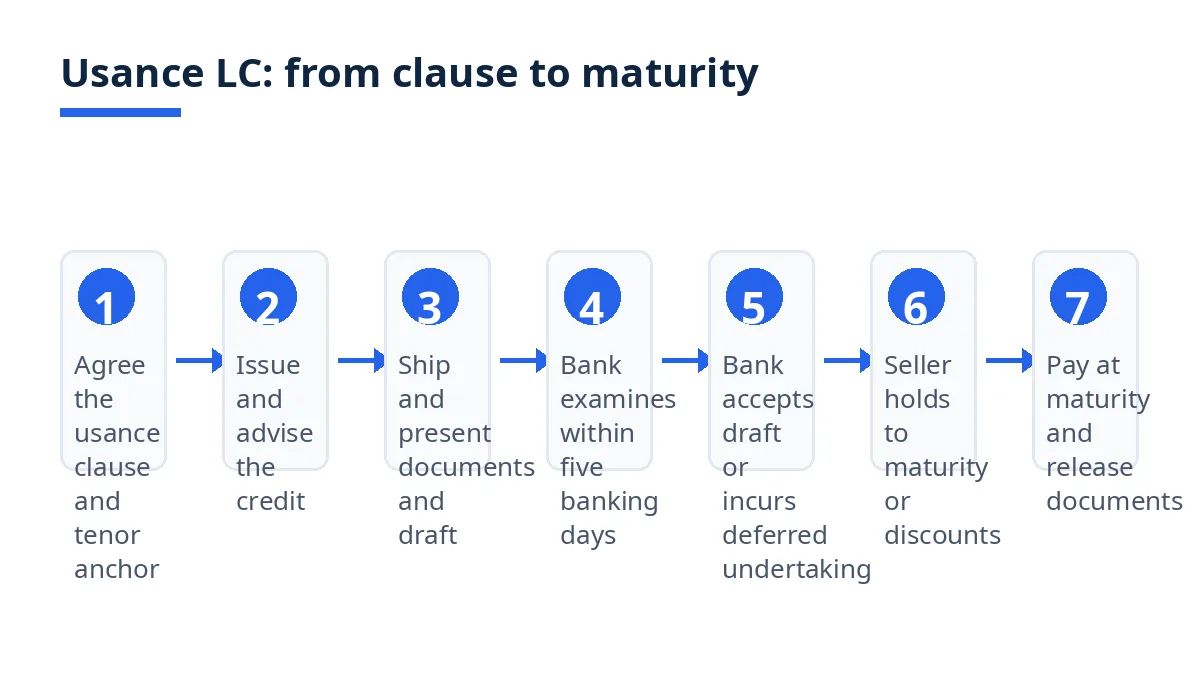
Agree the usance form and the tenor anchor in the contract clause. State deferred payment or acceptance, tenor length, and anchor: after the transport document date, after presentation, after acceptance, or after sight. Add currency, amount, dates, documents, ports, and confirmation. A clause saying only "90 days usance" is incomplete, because the anchor decides the maturity date.
Apply through your bank and confirm the facility, charges, and maturity funding plan. Ask your bank, in writing, for its full charge schedule, including any acceptance commission, and the date funds must be available. A confirming bank adds its own undertaking in addition to that of the issuing bank.3 If your bank cannot issue on the agreed tenor, renegotiate it before shipment.
Have the seller check the issued credit line by line, before production ends. Your bank sends the credit to a bank in Bangladesh, which advises it to the seller. An advising bank that is not a confirming bank advises without an undertaking to honour or negotiate.2 Ask the seller to confirm in writing that the tenor, anchor, documents, and any draft requirement are workable.
Track presentation, not only shipment. On shipment, the seller presents the document set the credit names through its bank. A credit must state whether it is available by sight payment, deferred payment, acceptance or negotiation.4 Deferred payment calls for no draft; acceptance calls for a time draft drawn on the bank named in the credit.4
Count the examination window from the day after presentation. Each examining bank has a maximum of five banking days following the day of presentation to determine if the presentation complies.2 A presentation including an original transport document must be made not later than 21 calendar days after shipment, and in any event not later than expiry.2 That window decides compliance, not the maturity date.
Get the maturity date confirmed in writing once acceptance or the deferred payment undertaking is incurred. On a complying presentation, the bank incurs the undertaking or accepts the draft, and the tenor clock starts from the anchor. Ask for that acceptance date, anchor, and maturity date in writing, and check it against your own calculation.
Fund the maturity date, and let the seller choose its financing path. At maturity the bank pays under the undertaking or accepted draft. Reimbursement for acceptance or deferred payment credits is due at maturity, whether or not the nominated bank prepaid or purchased before maturity.2 Seller discounting does not move your maturity date forward. Ask your bank in writing when documents will be released.
Costs, timelines and documents
Cost items to price before issuance
There is no universal usance letter of credit fee or timeline a guide can state as fact. Issuance, advising, confirmation, amendment, discrepancy, acceptance, and courier charges vary by bank, type, and amount. Usance adds usance interest for the credit period, and discount interest where the seller discounts. Ask each bank for its charges in writing before issuance, and write who bears each item into the contract. Do not assume the seller bears discount interest because the seller chose to discount, or the buyer bears usance interest because the buyer chose the tenor.
Timeline: the maturity clock and the tenor anchor
Timelines are set by the credit and the rules, not by a standard schedule. The fixed points are the latest shipment date, the 21-calendar-day presentation limit, expiry, the five-banking-day examination maximum, and the maturity date from the tenor anchor.2 Build your cash plan around maturity, not goods arrival.
Example figures: the same dates produce three different maturity dates when the anchor changes. Dates show structure only.
Tenor in the credit | Anchor | Maturity date |
|---|---|---|
90 days | After bill of lading date, 10 March | 8 June |
90 days | After presentation date, 17 March | 15 June |
90 days | After acceptance date, 20 March | 18 June |
Example figures: a USD 42,000 knitwear order, 90 days after bill of lading date, B/L 10 March, maturity 8 June. Example figures: a seller holding to maturity is paid 8 June; a seller discounting is paid sooner for a financing cost, while the buyer still pays 8 June.
Documents the credit names
The credit decides the document set. No fixed list applies to every usance credit, and a document not named in the credit will be disregarded. The usual set, where named, is the commercial invoice, transport document (bill of lading for sea, air waybill for air), packing list, and, where required, insurance document and certificate of origin. Add an inspection certificate only where the credit names issuer, timing, and wording, and a time draft only for acceptance.
A discrepant presentation earns no acceptance and no undertaking until the buyer waives the discrepancies or the seller re-presents a complying set before expiry. Data in a document must not conflict with data in another stipulated document or the credit.2 The commercial invoice description must correspond with the credit description.2 Copy the invoice description from the credit wording.
Bangladesh-specific rules and tips
Start with the seller bank file, which runs beside the credit. All exports from Bangladesh, unless exempted, must be declared on the EXP Form, and exporters undertake on it to repatriate full export proceeds within the period specified by Bangladesh Bank.5 The prescribed repatriation period is four months; without special or general authorization from Bangladesh Bank, late receipt exposes exporters to action under the Foreign Exchange Regulation Act, 1947.5
That four-month period is the check to run against a long tenor before issuance. A 90-day tenor normally sits inside four months, but a longer tenor, with presentation time and transit, can sit close to the limit. Ask the seller bank, through the seller, how a tenor approaching or passing four months will be handled.
Export payments may be received through an authorized dealer (AD) in freely convertible foreign currency, including Chinese Yuan, or in taka from a non-resident taka account.5 Before executing an export transaction, the AD must satisfy itself about realization arrangements, title documents, and buyer bona fides.5 Land or sea transport documents must generally be drawn to the order of an AD and handed to its authorized representative, and air waybills should be drawn to the order of a bank in the country of import nominated by the AD.5 A separate facility allows ADs, for shipment value up to USD 100,000 or equivalent and subject to conditions, to allow transport documents in the name of foreign importers.5 Do not assume the bill of lading will arrive in your name: ask how it will be drawn and endorsed.
For discounting, the circular gives the seller a defined route. Beneficiaries of usance export bills against direct and deemed exports of products produced in Bangladesh may discount bills for immediate financing through their ADs, subject to the circular's instructions, including that the bills derive from bona fide export transactions.5 Customer discounting expenses shall not exceed a markup of 3.00 percent over the benchmark rate, such as SOFR or Euribor, all-in cost.5 General permission is also granted to assign those rights to a licensed bank or financing institution abroad, provided it has fully prepaid the bill as a final, without-recourse settlement.5
One sector note: for raw jute and jute goods, the repatriation period may be up to 360 days against an irrevocable confirmed letter of credit or under open account.5 ADs shall conduct extended due diligence on usance terms in that context, including price competitiveness and usance interest commensurate with the prevailing currency rate.5 Do not read that period as a general tenor for other goods.
Mistakes and red flags
Writing "90 days usance" with no anchor. A tenor without an anchor has no maturity date until a bank interprets it. Name anchor, tenor length, and form in contract and credit, and confirm maturity in writing after acceptance.
Treating acceptance as payment. Acceptance, or a deferred payment undertaking, is a promise to pay at maturity, not money in the seller account. A seller planning production or the next order on an acceptance date, without a discount arrangement, faces a cash gap for the full tenor. A buyer treating acceptance as payment misstates its own cash plan.
Case at acceptance: a description mismatch that stops the tenor clock. Example figures: a usance credit available by acceptance describes the goods as "100% cotton terry bath towels, 600 GSM", while the presented invoice says "terry towels" only. Example figures: the bank treats the invoice description as not corresponding with the credit, so it does not accept the draft and no maturity date is fixed. Example figures: the seller has shipped, the tenor has not started, and the goods sit behind documents the buyer cannot yet use. The fix is a waiver inside the window or a corrected invoice re-presented before expiry.
Waiving without reading the refusal notice. When a bank decides to refuse to honour or negotiate, it must give a single notice to the presenter.2 A bank may approach the applicant for a waiver, but that approach does not extend the examination period.2 Read every discrepancy and answer in writing inside the window.
Assuming discounting moves the buyer payment date. Discounting changes when the seller receives funds, not when the buyer pays. Reimbursement for acceptance or deferred payment credits is due at maturity, whether or not the nominated bank prepaid before maturity.2
Checklist
Before you ask your bank to issue a usance credit, answer every line.
Usance form: deferred payment or acceptance, no sight wording.
Tenor length and anchor, with a worked maturity date.
Currency, amount, and quantity or amount tolerance stated in the credit.
Latest shipment date, expiry date, place for presentation, presentation period set with buffer.
Delivery term and named place, with ports and transhipment stated.
Document list complete: invoice, transport document, packing list, insurance, origin, or inspection only where named, plus a time draft for acceptance only.
Invoice description copied from the credit wording, not paraphrased.
Confirmation decision, with route and charge confirmed.
Bank charges allocated in the contract, charge by charge, including usance and discount interest.
Maturity funding plan: funds available at maturity, not at acceptance.
Written maturity confirmation to be requested after acceptance or undertaking.
Bangladesh file checked: EXP Form, transport document route, tenor against the four-month period, discount route where needed.5
Waiver process: who reads discrepancies, who decides, how fast the answer reaches your bank.
How Exportain helps
Post a free RFQ on Exportain at https://exportain.com/rfqs with your usance clause: deferred payment or acceptance, tenor length and anchor, latest shipment date, document list, delivery term, and named place. Suppliers quote against the same clause, so tenor disagreement surfaces at quotation stage.
Exportain platform payments are separate from your credit. The payment terms page covers membership payments and platform charges, not the bank undertaking between you and the seller.6
For the trust side, read buyer protection for what Exportain checks and records: supplier verification submissions reviewed by the Exportain team, a recorded quotation history, private document storage, and a route to report problems.7 A badge is a record of checks reviewed, not a guarantee.7
FAQs
What should I know first about usance LC?
A usance letter of credit is a bank undertaking to pay at a determinable future date on a complying presentation, not at presentation.3 Under UCP 600, honour for deferred payment means incurring a deferred payment undertaking and paying at maturity, and for acceptance means accepting a draft and paying at maturity.2
What are the typical costs and timelines?
There are no typical usance costs or timelines a guide can state as fact, because charges vary by bank, letter of credit type, and amount. The fixed points are the latest shipment date, the 21-calendar-day presentation limit, expiry, the five-banking-day examination maximum, and the maturity date from the tenor anchor.2 Usance and discount interest are priced by the banks and allocated in the contract before issuance.
Which documents are needed?
Only the documents the credit names, each matching the credit: invoice, transport document, packing list, and, where required, insurance, origin, and inspection documents, plus a time draft for acceptance only.4 Data in a document must not conflict with data in another stipulated document or the credit.2 On the Bangladesh side, the export is declared on the EXP Form through the seller AD bank, and transport documents are generally drawn to the order of that AD.5
What are the most common mistakes?
The most common mistakes are writing a tenor with no anchor, treating acceptance as payment, waiving discrepancies without reading the refusal notice, and assuming discounting moves the buyer payment date.
Next steps on Exportain
Post a free RFQ on Exportain at https://exportain.com/rfqs with your usance clause, tenor anchor, latest shipment date, and document list. Before you confirm, read the letter of credit (LC) guide, and buyer protection for what Exportain checks and records.7
Sources
- ICC's new rules on documentary credits now available. International Chamber of Commerce, (accessed )
- Uniform Customs and Practice for Documentary Credits (UCP 600). LegalGuide (accessed )
- A guide to types of documentary credit. ICC Academy (accessed )
- Availability of Letters of Credit. Letter of Credit Consultancy Services (accessed )
- Consolidated circular on foreign exchange regulations — export trade transactions (FEPD-1 Circular No. 26, July 30, 2026). Bangladesh Bank (accessed )
- Payment and Membership Terms. Exportain (accessed )
- Buyer protection: What Exportain does to protect buyers. Exportain (accessed )
About the author
Sourcing from Bangladesh?
Post a request for quotation and suppliers on Exportain can send you their quotes directly.
Post an RFQ