LC Meaning (Letter of Credit): LC Payment, Types, Documents and How It Works
Definition
LC meaning in one sentence: LC means Letter of Credit — a bank's written undertaking to pay a seller a stated amount, provided the seller presents documents that comply exactly with the terms of the credit, on time and at the stated place.
By Naim Islam
Published Updated 10 min read
On this page
LC meaning in one sentence: LC means Letter of Credit — a bank's written undertaking to pay a seller a stated amount, provided the seller presents documents that comply exactly with the terms of the credit, on time and at the stated place.
If you are importing from Bangladesh for the first time, that matters: you ask your bank to replace your payment promise with its own; the factory trusts the bank's undertaking only if documents comply; almost every LC delay, fee and dispute comes from documents, not goods, trigger payment.
This guide covers LC under UCP 600, LC payment meaning, the parties, the process, types, the LC document checklist, discrepancies, and FAQs.
What Is the Meaning of LC?
LC stands for Letter of Credit. UCP 600 Article 2 defines a credit as any arrangement that is irrevocable and thereby constitutes a definite undertaking of the issuing bank to honour a complying presentation.
Irrevocable: Every credit is irrevocable under UCP 600 even if not stated; it cannot be amended or cancelled without agreement; the revocable UCP 500 form no longer applies.
Definite undertaking: The bank honours — pay at sight, incur a deferred payment undertaking and pay at maturity, or accept a draft and pay at maturity — on a complying presentation; Article 4: a credit is separate from the sale contract.
Complying presentation: A presentation in accordance with the credit terms, UCP 600 and ISBP; if it does not comply, the bank may refuse, subject to the Article 16 notice procedure.
Article 5: Banks deal with documents, not goods, services or performance; if documents comply on their face, the bank must honour. For quality, require an independent inspection certificate as an LC document, stating the issuer, timing and what it certifies; an LC protects payment discipline, not product quality.
LC Payment Meaning
LC payment meaning is payment by a bank against documents as stated in the credit, not the buyer pays the seller directly on goods arrival. Article 6: a credit must state availability, the nominated bank, the presentation place and expiry.
At sight: The bank pays after determining compliance, with a maximum of five banking days following presentation to determine compliance.
Deferred / usance: The bank incurs a deferred payment undertaking on a complying presentation and pays at maturity, for example days after the BL date; no draft is required.
Acceptance: The seller draws a time draft on the specified bank, the bank accepts it on a complying presentation and pays at maturity.
Negotiation: A nominated bank purchases drafts and / or documents under a complying presentation by advancing, or agreeing to advance, funds.
LC at sight means: ship, present the exact documents before expiry, and, if the presentation complies, be paid without waiting for goods arrival. Usance means the same presentation, but payment at maturity; suppliers price usance differently. LC payment does not mean goods have cleared customs; the buyer needs the same documents, above all the transport document, to take delivery.
Who Are the Parties?
Applicant: The buyer / importer on whose request the credit is issued.
Issuing bank: The buyer's bank; it issues the credit and undertakes to honour a complying presentation.
Beneficiary: The seller / exporter in whose favour the credit is issued; it ships and presents documents.
Advising bank: Usually in the seller's country, it advises the credit at the issuing bank's request; Article 9 signifies it is satisfied as to apparent authenticity; it gives no undertaking to pay.
Confirming bank: At the issuing bank's request, it adds its own undertaking in addition to the issuing bank's (Article 8).
Nominated bank: The bank with which the credit is available, or any bank if the credit is available with any bank; nomination alone does not oblige it to honour or negotiate unless it is a confirming bank or has expressly agreed (Article 12).
LC Process Step-by-Step
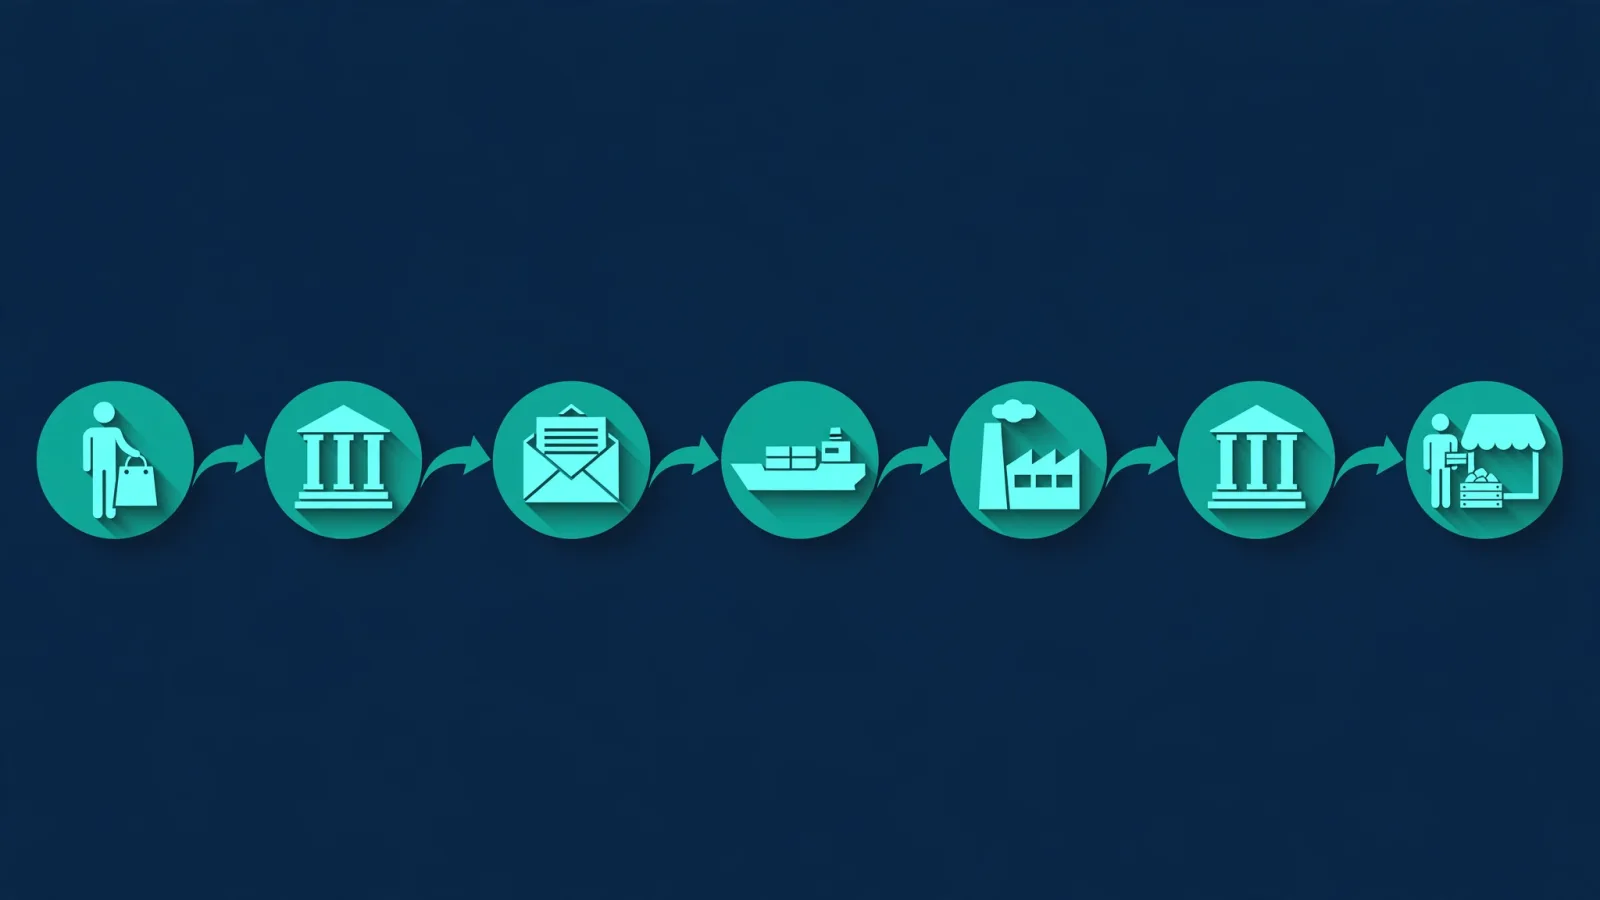
Step 1 Contract: Buyer and seller agree goods, price, Incoterm, ports, shipment date, LC payment and documents.
Step 2 Application: The buyer applies to the issuing bank; the application mirrors the contract.
Step 3 Issuance: The issuing bank sends the credit by SWIFT, commonly MT700, to the advising bank, usually subject to UCP 600.
Step 4 Advice: The advising bank advises the seller, authenticity checked; a confirming bank adds its undertaking if requested.
Step 5 LC check: The seller checks every field against the contract; an amendment is requested before shipment if needed.
Step 6 Shipment: The seller ships by the latest shipment date; the carrier issues the transport document.
Step 7 Documents: The seller assembles the invoice, packing list, transport document and other required documents.
Step 8 Presentation: The seller presents to the bank at the stated place, within the presentation period and before expiry.
Step 9 Examination: The bank examines the documents alone for compliance, Article 14, maximum five banking days.
Step 10a Complying: The bank honours or negotiates; documents are forwarded and released to the buyer.
Step 10b Discrepant: The bank seeks a waiver, or refusal by a single Article 16 notice; re-presentation only if time allows.
Step 11 Delivery: The buyer takes delivery and clears customs with the documents.
Deadlines: If the credit states a presentation period, present within it; if none, Article 14(c) requires presentation including original transport documents not later than 21 calendar days after shipment, and in any event not later than expiry; after expiry a presentation never complies, even if shipment was on time.
Types of LC Comparison
Irrevocable: Cannot be amended or cancelled without agreement; it is the only form under UCP 600 and is the standard.
Confirmed: A second bank adds its undertaking; the seller wants a local bank undertaking; extra charges apply.
Unconfirmed: The advising bank adds no undertaking.
Sight: Paid once a complying presentation is determined; faster payment.
Usance / Deferred: Payment at the stated maturity; the buyer needs time, the seller waits.
Acceptance: A time draft is accepted and paid at maturity.
Transferable: The first beneficiary may transfer the credit in whole or in part to second beneficiaries, Article 38; the credit must expressly state transferable; for trading companies; it can be transferred only once.
Back-to-Back: A separate, independent LC is opened to an input supplier against the master LC; it is not a transfer; used in Bangladesh for garments, fabric and accessory LCs.
Revolving: The amount reinstates after each drawing, as stated; for repeat shipments.
Standby: Pays against documents evidencing non-performance or default; usually under ISP98 or UCP 600; used as performance or advance security.
Red / Green Clause: An advance is made before shipment documents; the green clause also covers warehousing; pre-shipment finance; less common.
LC Document Checklist
The credit itself is the authority; the standards are Articles 18-28; Article 14(g): a document presented but not required by the credit will be disregarded and may be returned.
Commercial invoice, Article 18: Issued by the beneficiary to the applicant, in the credit currency; the goods description must correspond with the credit description; do not paraphrase it; copy the credit description.
Transport document: Bill of lading, Article 20; air waybill, Article 23; road / rail, Article 24; it must show the carrier, on-board shipment at the stated port, the stated ports, the sole original or full set, and must not evidence a prohibited transshipment or partial shipment.
Packing list: Article 14 data must not conflict; weights, cartons and marks must match the invoice and the transport document.
Certificate of origin: Consistency is required; any issuer and content the credit specifies; a named issuer must be the actual issuer.
Insurance, Article 28, if required: Issued by an insurer, underwriter or agent; at least 110% of the CIF or CIP value where determinable; effective by the shipment date; no cover notes; the seller insures on CIF / CIP, the buyer typically insures on FOB / EXW.
Inspection certificate, if required: Issuer and content as specified; no conflicts; state what was certified, by whom, and the pre-shipment timing.
Other certificates: As worded in the credit; sign and date only where required.
Draft, where required: Correct drawee, amount and tenor; a draft is not needed for sight or deferred payment unless stated.
Cross-cutting: Data need not be identical but must not conflict, Article 14(d); copy names, ports and references exactly; Article 17: at least one original of each stipulated document.
Discrepancies
A discrepancy is any failure to comply: late shipment, presentation after expiry or after the presentation period, wrong port, an invoice description that does not correspond, conflicting data, a missing document, or a transport document evidencing a prohibited condition.
Article 16: The bank may approach the applicant for a waiver, but the applicant is not obliged to accept it; if the bank refuses, it must give a single notice stating the refusal, each discrepancy, and how the documents are held, no later than the close of the fifth banking day after presentation; a bank failing Article 16 is precluded by Article 16(f) from claiming non-compliance.
Sellers: Check the LC on arrival, request amendments early, prepare documents from the LC wording, and present early. Buyers: Draft performable instructions and decide waiver handling in advance. Article 10: An amendment does not bind the beneficiary until accepted; partial acceptance is not allowed; silence is not acceptance.
LC Costs Who Pays What
Several banks and intensive checking mean an LC costs more than a simple transfer; charges vary by bank, so ask for the tariff. Typical charges are issuing, advising, confirmation, negotiation / checking, amendment, discrepancy and courier charges.
State in the contract and the application which charges are for the applicant and which are for the beneficiary; Article 37(c): if beneficiary charges cannot be collected, the issuing bank remains liable; avoid vague wording such as all charges to beneficiary.
LC vs TT and Other Payment Methods
TT: A direct bank payment, often a deposit before production and the balance against shipment documents or after shipment; simpler and cheaper; the buyer carries more risk on the deposit, the seller carries more risk on the post-shipment balance.
Open account: Suits long-standing relationships; it exposes the seller most.
Documentary collection: Under URC 522 where stated; banks handle documents but give no undertaking; it sits between TT and LC.
For a first substantial order with a new supplier, an LC is often worth the cost; for samples or a repeat order with a proven supplier, TT is common. Write the term in full: LC at sight, or 30% TT deposit, 70% against bill of lading copy.
LCs in Bangladesh Trade
Garment exports from Bangladesh run heavily on LCs. A factory receiving a master export LC typically opens back-to-back LCs for fabric and accessories, within Bangladesh Bank FX guidelines and bonded warehouse arrangements where applicable. A late or incorrect master LC cascades: input LCs are delayed, production is delayed, and the shipment date shrinks; issuing a clean LC early protects delivery.
Bangladeshi banks check that the Incoterm matches the shipment method and that documents meet Bangladesh Bank requirements. Treat a supplier amendment request on ports or wording as compliance, not stalling, and respond quickly.
How Exportain Helps
Exportain connects buyers with verified Bangladeshi sellers and providers. Align the terms before applying: the exact goods description, with the same wording in the LC and the invoice, the quantity, ports, latest shipment date, the document list, and sight or usance; this prevents most amendments and discrepancies.
Ready to source from Bangladesh? Post an RFQ on Exportain and receive quotes from suppliers who can work on clear LC terms.
Frequently Asked Questions
What is l/c meaning?
L/C meaning is Letter of Credit. The slash abbreviation style is the same instrument: a bank's irrevocable undertaking under UCP 600 to honour a complying presentation, up to the amount stated.
What is the meaning of LC?
LC is a conditional bank payment promise: the issuing bank undertakes to pay the seller if, and only if, the seller presents documents complying with the credit terms, UCP 600 and ISBP, at the stated place and before expiry.
What is LC payment meaning?
LC payment meaning is payment by a bank against documents, not by the buyer directly on receipt of the goods: at sight after compliance is determined, deferred at maturity, by acceptance of a time draft, or by negotiation; banks examine the documents alone, in a maximum of five banking days.
What is an LC document?
An LC document is any document the credit requires, typically a commercial invoice, a transport document and a packing list, and, where called for, a certificate of origin, insurance and an inspection certificate; each is examined under its UCP article; data must not conflict; a document that is not required will be disregarded.
What are letters of credit?
Letters of credit is the plural, full-form name for LCs, also called documentary credits; they are all types issued by banks to support trade; one transaction uses one letter of credit.
Is an LC a guarantee that goods are good quality?
No. Article 5: banks deal with documents, not goods. An LC ensures payment follows compliant documents; it does not inspect the goods. Require an independent pre-shipment inspection certificate as an LC document, and run your own quality process.
What happens if LC documents have a discrepancy?
The bank may seek the applicant's waiver, or refuse under Article 16, by a single notice listing each discrepancy and stating how the documents are held, by the close of the fifth banking day after presentation. The seller can correct and re-present only if the presentation period and expiry allow; otherwise payment, document release and delivery are delayed.
Sources
- Letter of Credit. International Trade Administration, U.S. Department of Commerce (accessed )
- Methods of Payment. International Trade Administration, U.S. Department of Commerce (accessed )
- UCP 600 - Uniform Rules for Documentary Credits (publication page and table of contents). ICC Knowledge 2 Go, International Chamber of Commerce (accessed )
- Set of Guidance Papers on Recommended Principles and Usages around UCP 600. International Chamber of Commerce, (accessed )
- Guidelines for Foreign Exchange Transactions (GFET) 2018, Vol. 1, Chapter 8, Section I: Exports. Bangladesh Bank (accessed )
- Guidelines for Foreign Exchange Transactions (GFET), 2018 Vol. 1, Chapter 7, Section III: Back to Back LCs. Bangladesh Bank (accessed )
- Online UD: Utilization Declaration. Bangladesh Knitwear Manufacturers & Exporters Association (BKMEA) (accessed )
Reviewed by Nourin Tabassum
About the author
Sourcing from Bangladesh?
Post a request for quotation and suppliers on Exportain can send you their quotes directly.
Post an RFQ