Using Confirmed LC When Buying From Bangladesh: Bank Rules and Tips
Confirmed LC for Bangladesh buyers: how a second bank undertaking is requested and authorized, what it changes at presentation, and the mistakes that leave a credit unconfirmed.
Short answer
A confirmed letter of credit gives a Bangladeshi seller a second bank undertaking, in addition to the issuing bank undertaking. This guide explains how confirmation is requested and authorized under UCP 600, what a confirming bank must honor, how charges and timelines are confirmed with each bank, and the mistakes that leave a credit unconfirmed.
On this page
Key takeaways
A confirmed LC gives the seller a second, definite bank undertaking in addition to the issuing bank's: the confirming bank acts upon the issuing bank's authorization or request and is irrevocably bound from the time it adds its confirmation.
Advice alone is not confirmation, and a silent confirmation is not a UCP 600 confirmation: advice carries no undertaking, while silent confirmation is a separate agreement between the beneficiary and its bank, outside UCP 600.
No confirmation charge, margin, or approval condition is universal: confirm every charge, who bears it, and the confirmation decision in writing with each bank before the seller ships.
Confirmation does not cure a discrepant presentation, inspect goods, extend expiry, or move a maturity date, and an amendment is unconfirmed unless the confirming bank extends its confirmation to it.
A confirmed letter of credit (LC) adds a second bank promise to the first one. The issuing bank, the buyer's bank, already undertakes to honor a complying presentation. When a second bank confirms the credit, the seller, as beneficiary, can look to that bank's own undertaking as well. That second undertaking is the subject of this guide: why a beneficiary asks for it, how it is requested and authorized, and what it changes at presentation.
Under UCP 600, the Uniform Customs and Practice for Documentary Credits, 2007 Revision, confirmation means a definite undertaking of the confirming bank, in addition to that of the issuing bank, to honor or negotiate a complying presentation.1 A confirming bank is the bank that adds its confirmation to a credit upon the issuing bank's authorization or request, and it is irrevocably bound from the time it adds its confirmation.1 This guide covers that confirmation angle only, for a buyer ordering from Bangladesh. For the short definition of an LC, see the letter of credit (LC) guide.
Why this matters for buyers and sellers
For the seller in Bangladesh, confirmation changes whose promise stands behind the shipment. An unconfirmed credit leaves the seller with the issuing bank's undertaking alone. A confirmed credit gives the seller a local point of claim: present complying documents to the confirming bank, and that bank must honor under its own undertaking. That is why sellers ask for confirmation on a first order or an order where the issuing bank or its country carries risk the seller does not want to carry alone.
For the buyer, confirmation changes cost and control, not the goods bargain. The buyer still pays, through the banks, only when documents comply. Banks deal with documents and not with goods, services or performance to which the documents may relate.1 What the buyer gains is a seller willing to ship on bank terms.
For the confirming bank, confirmation is a decision, not a formality. A bank authorized or requested by the issuing bank to confirm a credit, but not prepared to do so, must inform the issuing bank without delay and may advise the credit without confirmation.1 No party can assume a bank will confirm.
Confirmed, advised-only, and silent confirmation
Form | Who authorized it | What the seller gets | UCP 600 position |
|---|---|---|---|
Confirmed LC | Issuing bank authorized or requested the confirming bank | A definite undertaking from the confirming bank, in addition to the issuing bank | Article 8 confirming bank undertaking |
Advised-only (unconfirmed) LC | Issuing bank asked a bank only to advise | Advice only, with no undertaking to honor or negotiate | Article 9: advising without any undertaking |
Silent confirmation | The beneficiary's own bank, without the issuing bank's request or authorization | A separate agreement with that bank only | Outside UCP 600 |
The distinction between the second and third rows is the one most often missed. An advising bank that merely forwards the credit gives no payment promise. A silent confirmation, by contrast, is a bank's agreement to honor or negotiate a beneficiary's complying presentation even though the issuing bank did not request or authorize confirmation, and it is silent to the issuing bank.2 That agreement is a side agreement between only the beneficiary and the bank providing it, and it lies outside UCP 600.2 A seller holding one must read that bank's own letter for its terms, limits, and expiry, and must not describe it to a buyer as a UCP 600 confirmation.
A confirmed credit is still one credit with two undertakings behind it, unlike a back-to-back structure of two separate credits or a transferable credit transferred to a second beneficiary.
Step-by-step: how it works
Confirmation is arranged before shipment and tested at presentation.
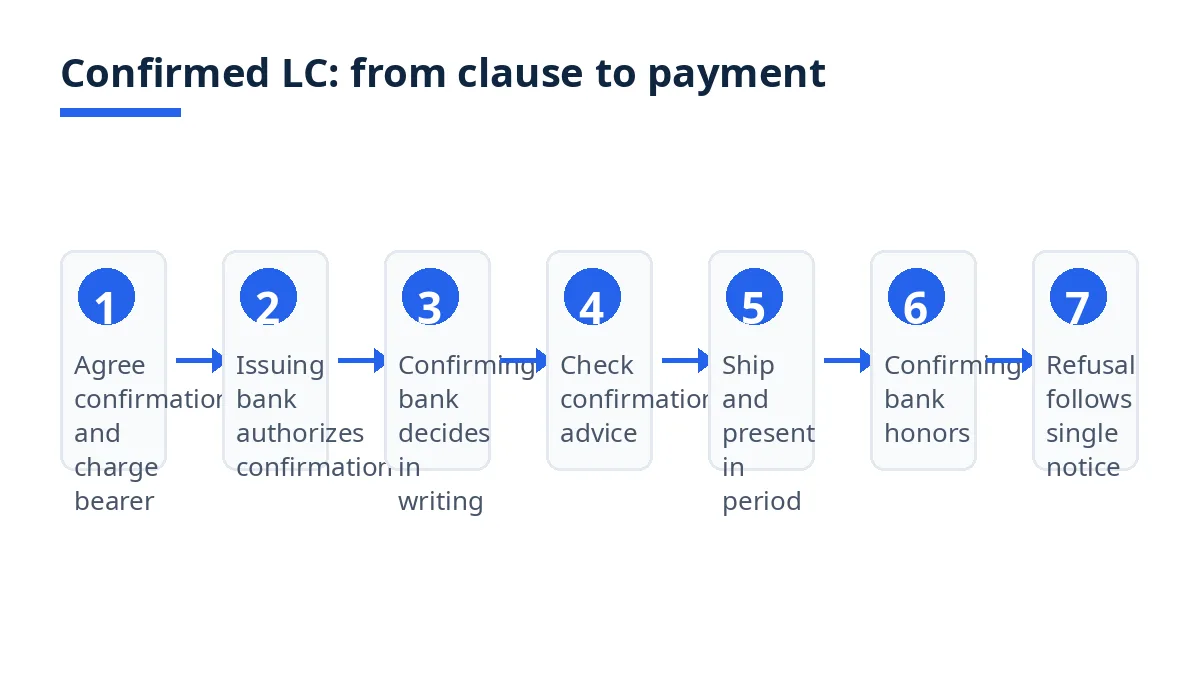
Write confirmation into the contract clause, before any bank form. State that the credit is to be confirmed, name the expected confirming bank where the parties can agree it, and state who bears the confirmation charge. State the availability form as well: sight payment, deferred payment, acceptance, or negotiation, because the confirming bank's duty follows that form.
Let the beneficiary ask, and the issuing bank authorize. The seller, as beneficiary, asks for confirmation through its bank, and the buyer asks the issuing bank to authorize or request that bank to confirm. Confirmation cannot be created by the beneficiary alone under UCP 600: the confirming bank acts upon the issuing bank's authorization or request.1 If the issuing bank will not authorize confirmation, the parties must renegotiate the payment term before shipment.
Wait for the confirming bank's decision, in writing. The confirming bank decides whether to add its undertaking. If it is not prepared to confirm, it must inform the issuing bank without delay and may advise the credit without confirmation.1 The seller should not start production on the assumption that confirmation will follow.
Check the confirmation advice line by line, including its scope. Confirm that the advice states the confirming bank has added its confirmation, that it covers the full credit amount or states the confirmed portion if partial, and that availability, expiry, and place for presentation match the credit. Ask, in writing, what happens on amendment, because a confirming bank may extend its confirmation to an amendment, or advise an amendment without extending it, in which case it must inform the issuing bank without delay and inform the beneficiary in its advice.1
Ship and present to the right bank, inside the presentation period. The seller ships by the latest shipment date and presents the documents the credit names to the confirming bank or to any other nominated bank, within the presentation period and before expiry. A presentation including an original transport document must be made not later than 21 calendar days after shipment, and in any event not later than expiry. Each examining bank has a maximum of five banking days following presentation to determine if a presentation is complying.1
Let the confirming bank honor under its own undertaking. On a complying presentation, the confirming bank must honor where the credit is available with it, negotiate without recourse where it is available by negotiation with it, and honor where the credit is available with another nominated bank and that bank does not act as required.1 For a sight credit, honor means payment at sight. For a deferred payment credit, honor means incurring a deferred payment undertaking and paying at maturity. For an acceptance credit, honor means accepting the draft drawn by the beneficiary and paying at maturity.1
Handle a discrepant presentation through the refusal procedure, not by assumption. If a nominated bank, a confirming bank, or the issuing bank decides to refuse to honor or negotiate, it must give a single notice to that effect to the presenter.1 The notice states the refusal, each discrepancy, and how the documents are held. Confirmation does not cure a discrepancy: it strengthens the promise to pay a complying presentation, and a non-complying presentation is not one.
Costs, timelines and documents
No confirmation charge, margin, or approval condition in this guide is stated as a universal figure, because none is universal. Every bank-specific item below is a "confirm with the confirming or issuing bank" item, settled in writing before the seller ships.
The charge items to price and allocate in the contract are the issuing, advising, confirmation, examination or negotiation, amendment, discrepancy, and courier charges. Under UCP 600, a bank instructing another bank to perform services is liable for the charges incurred by that bank, and if a credit states that charges are for the account of the beneficiary and they cannot be collected or deducted from proceeds, the issuing bank remains liable for payment of charges.1
The timeline has three clocks. The first is shipment to presentation, ending not later than 21 calendar days after shipment where an original transport document is included, and in any event not later than expiry. The second is examination: a maximum of five banking days following presentation. The third is payment: at sight on honor for a sight credit, or at maturity for a deferred payment or acceptance credit, with reimbursement due at maturity whether or not a nominated bank prepaid or purchased before maturity.1 Confirmation does not shorten examination, extend expiry, or move a maturity date.
The document list is the credit's list, not a separate confirmation list. Confirmation adds an undertaking, not a document. The documents commonly named are the commercial invoice, the transport document, and the packing list, plus a certificate of origin, an insurance document, or an inspection certificate where called for. Each document must not conflict with the credit or with another stipulated document.
Example figures, for illustration only: a buyer orders canvas tote bags for USD 40,000 on a confirmed sight LC, and if the contract is silent on the confirmation charge, the seller may learn at advice that the charge falls on the beneficiary.
Bangladesh-specific rules and tips
On the Bangladesh side, the seller's bank is usually also the authorized dealer (AD) bank handling the export file. Exports from Bangladesh are generally declared on the EXP Form, and the AD bank handles the export documents and reporting to Bangladesh Bank.3 Within 14 days from shipment, exporters submit the signed EXP Form together with the bill of export and relevant shipping documents to the AD bank, and shipping documents declared on the EXP Form must be passed through AD banks within 14 days from shipment.3 A confirmed credit does not change those deadlines.
The prescribed period for repatriating export proceeds is four months, unless a longer period is specifically permitted.3 For a confirmed deferred payment or acceptance credit, check that period against the tenor: a maturity date beyond it needs the AD bank's guidance before issuance, not after acceptance. For a confirmed sight credit, the repatriation clock still runs from shipment.
Ask the seller to name its AD bank and the bank expected to confirm, and whether they are the same bank.
Mistakes and red flags
Treating advice as confirmation. An advising bank that is not a confirming bank advises without any undertaking to honor or negotiate.1 If the advice does not state that the bank has added its confirmation, there is no confirmation.
Assuming a bank will confirm. A bank authorized or requested to confirm may decline, and must then inform the issuing bank without delay.1
Calling a silent confirmation a UCP 600 confirmation. A silent confirmation is a separate agreement between the beneficiary and its bank, outside UCP 600.2
Ignoring the amendment gap. A confirming bank may advise an amendment without extending its confirmation.1 An increased amount or later shipment date added by amendment is unconfirmed unless the confirming bank extends its confirmation to it.
Assuming confirmation covers discrepancies or quality. Confirmation strengthens the promise to pay a complying presentation. It does not waive a discrepancy, and it does not inspect goods.1
Presenting to the wrong bank or after expiry. Presentation must be made to the right bank on or before expiry, or it does not earn honor under the confirming bank's undertaking.
Leaving the confirmation charge unallocated. If the contract does not state who bears the confirmation charge, the deduction surprises one side at advice or at payment.
Checklist
State confirmation, the expected confirming bank, and the availability form in the contract clause.
State who bears the confirmation charge and every other bank charge, in the contract and the credit application.
Have the buyer ask the issuing bank to authorize confirmation, and the seller ask its bank to confirm.
Wait for the written confirmation advice before the seller starts production on confirmed terms.
Check the confirmation advice for amount coverage, availability, expiry, and presentation place.
Confirm, for every amendment, whether the confirming bank extends its confirmation to it.
Ship by the latest shipment date and present within the presentation period and before expiry.
Prepare every document from the credit wording, not from the sale contract alone.
Confirm the EXP Form, the AD bank's 14-day steps, and the four-month repatriation period with the seller's AD bank.
Keep the credit, the confirmation advice, every amendment advice, the document set, and all bank correspondence together.
How Exportain helps
Exportain connects buyers with Bangladeshi sellers and providers, and the quotation record is the place to agree the confirmation requirement and the charge allocation before any bank form is drafted. Platform membership and payment terms are separate from the bank undertaking: Exportain's Payment and Membership Terms cover payments to Exportain and memberships, not money paid directly between two companies outside the platform.4 The Buyer Protection page states that a badge is a record of checks reviewed, not a capacity, quality, or delivery guarantee.5
Post a free RFQ on Exportain to start a sourcing conversation with suppliers who can work on confirmed LC terms: Post a free RFQ.
FAQs
What should I know first about confirmed LC?
A confirmed LC gives the seller a second bank undertaking, in addition to the issuing bank's. The confirming bank adds its definite undertaking upon the issuing bank's authorization or request, and is irrevocably bound from the time it adds its confirmation.1 Confirmation changes who must honor a complying presentation; it does not inspect goods, and does not cure a discrepant presentation.
What are the typical costs and timelines?
There are no universal confirmation charges or timelines to quote, because each bank sets its own schedule and conditions. Confirm the issuing, advising, confirmation, examination, amendment, discrepancy, and courier charges in writing with each bank, and state who bears each item in the contract. For timelines, allow presentation not later than 21 calendar days after shipment where an original transport document is included, a maximum of five banking days of examination following presentation, and payment at sight or at maturity according to the availability form.1
Which documents are needed?
The credit itself states the required documents, so the answer is the document list in the credit, not a fixed universal list: commonly the commercial invoice, transport document, and packing list, plus a certificate of origin, insurance document, or inspection certificate where called for. Confirmation adds an undertaking, not a document. The seller's AD bank handles the EXP Form file.3
What are the most common mistakes?
The most common mistakes are treating advice as confirmation, assuming a bank will confirm, calling a silent confirmation a UCP 600 confirmation, ignoring an unextended amendment, assuming confirmation covers discrepancies or quality, presenting to the wrong bank or after expiry, and leaving the confirmation charge unallocated.
Next steps on Exportain
Start with the confirmation decision, then take it to the banks. Read the letter of credit (LC) guide, check the Payment and Membership Terms and Buyer Protection pages, and Post a free RFQ.
Sources
- Uniform Customs and Practice for Documentary Credits (UCP 600). LegalGuide (accessed )
- Silent Confirmation Of Documentary Credits: It’s Still Happening. Documentary Credit World, (accessed )
- Consolidated circular on foreign exchange regulations — export trade transactions (FEPD-1 Circular No. 26, July 30, 2026). Bangladesh Bank (accessed )
- Payment and Membership Terms. Exportain (accessed )
- Buyer protection: What Exportain does to protect buyers. Exportain (accessed )
About the author
Sourcing from Bangladesh?
Post a request for quotation and suppliers on Exportain can send you their quotes directly.
Post an RFQ